Buying a House in Weston
A 1990s master-planned city where the roof and the tax reset drive the budget
A typical single-family house in Weston is worth about $802,363 on Zillow's home value index, almost flat over the past year at -0.8%. Over five years, Weston's all-homes value rose 29.5%, so most current owners bought for much less than today's prices.
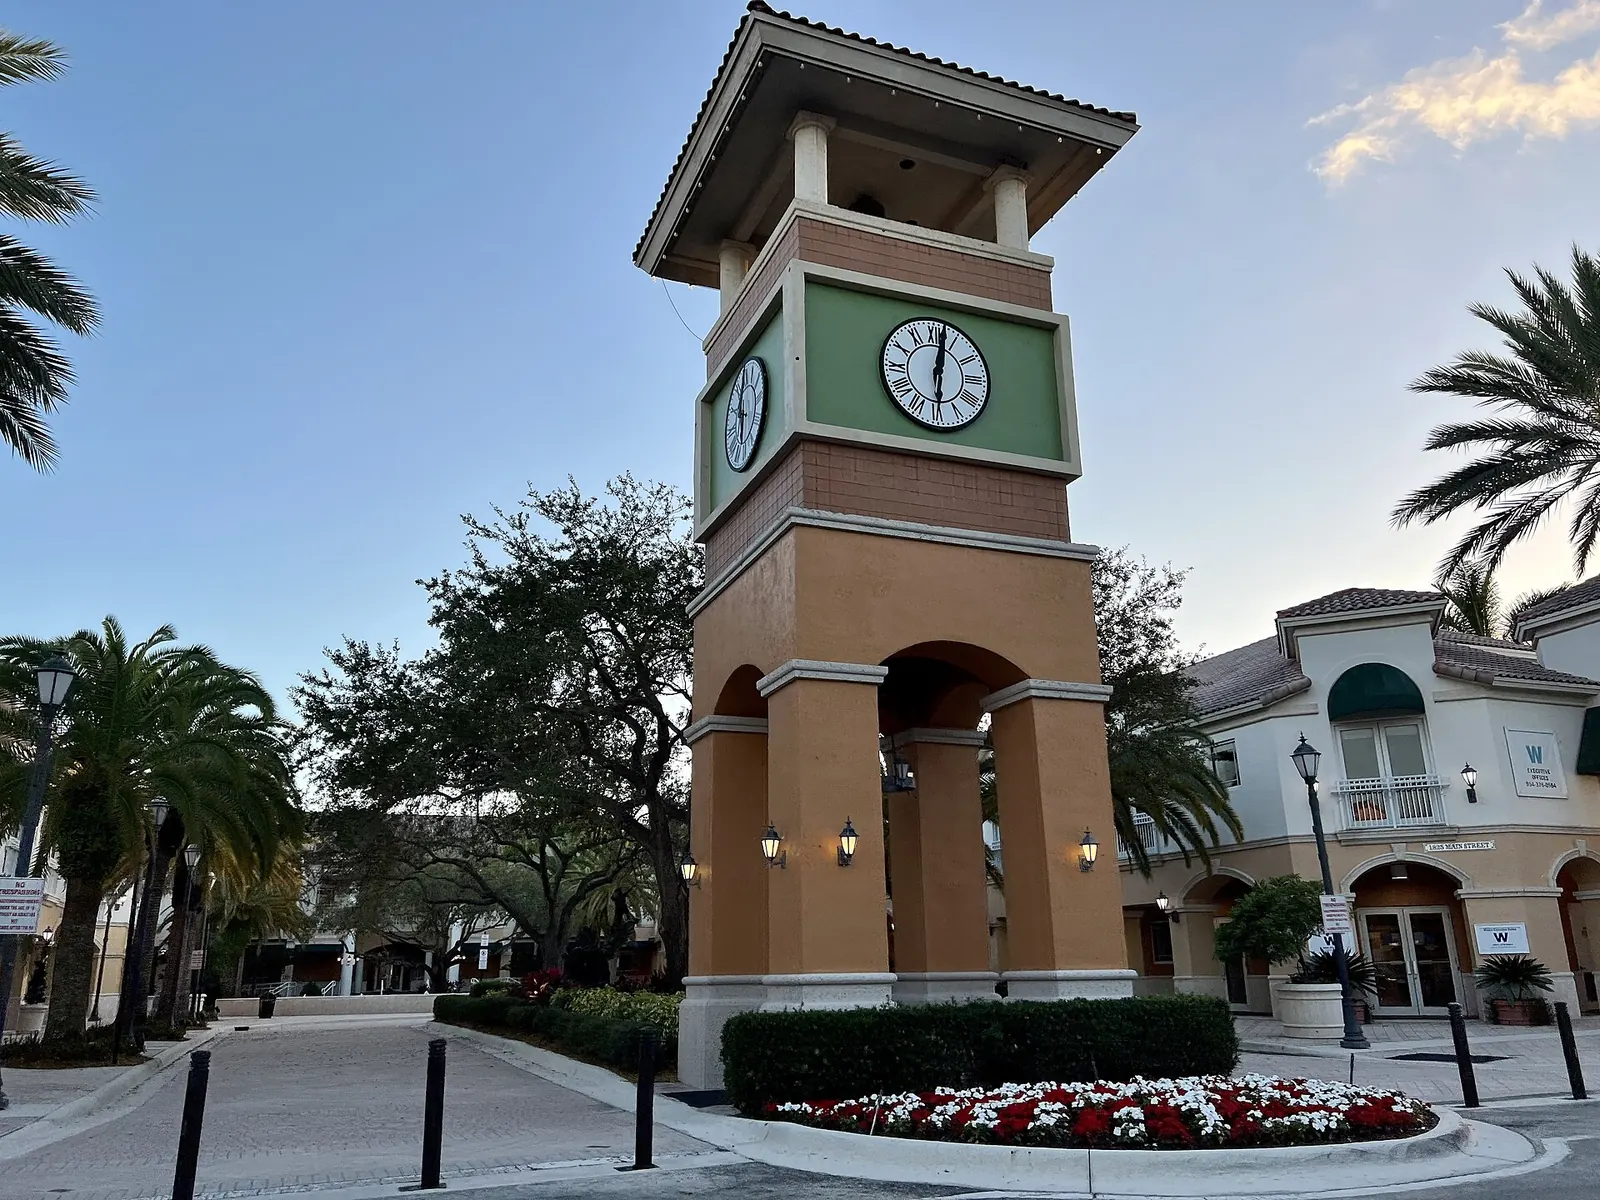
- Typical single-family home value
- $802K Weston, Zillow, September 2026
- Past year
- −0.8%
- Past 5 years
- +31%
- Lower third of the market
- $430K typical value
- Upper third
- $1.16M typical value
Price by bedrooms and the four-bedroom sweet spot
- 3 bedrooms: about $619,867
- 4 bedrooms: about $852,799
- 5 bedrooms or more: about $1,288,782
Moving from three to four bedrooms adds about $232,932. Moving from four to five adds about $435,983, because five-bedroom homes in Weston tend to sit on larger lakefront or estate lots in neighborhoods like Weston Hills, The Landings and Windmill Ranch Estates, where Zillow's typical values run well above $1 million. Four bedrooms is where most families land, and it is the busiest part of the market.
Zillow's lower third of Weston homes tops out near $429,734, which is mostly condos and townhouses. The upper third starts around $1,164,877. A detached house under $600,000 is uncommon here.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Single-family | All homes |
|---|---|---|
| Dec 2012 | $358,056 | $318,172 |
| Dec 2013 | $411,640 | $369,497 |
| Dec 2014 | $440,638 | $398,358 |
| Dec 2015 | $454,492 | $413,489 |
| Dec 2016 | $464,682 | $424,411 |
| Dec 2017 | $483,161 | $441,673 |
| Dec 2018 | $497,753 | $455,619 |
| Dec 2019 | $506,795 | $464,566 |
| Dec 2020 | $537,621 | $490,899 |
| Dec 2021 | $642,142 | $580,493 |
| Dec 2022 | $770,756 | $690,984 |
| Dec 2023 | $803,905 | $725,824 |
| Dec 2024 | $836,562 | $753,915 |
| Dec 2025 | $805,806 | $725,844 |
| Sep 2026 | $802,363 | $718,627 |
Houses from the 1990s: roofs, windows and plumbing
Census data puts Weston's median year built at 1995. Most of the city was built in the late 1980s through the early 2000s, so the typical house is around 30 years old. That age brings a predictable list for the inspection:
- Roof age: a tile roof can last longer than a shingle roof, but underlayment wears out. Ask for the permit date of the last roof replacement. Insurers price heavily on roof age, and an original roof can limit your carrier options.
- Wind mitigation: homes built before Florida's 2002 statewide building code often lack features like hip roof straps or impact-rated openings. A wind mitigation report shows what the house has, and each credit lowers the premium.
- Plumbing and water heaters: some 1990s houses used polybutylene supply lines, which many insurers refuse. Your inspector should identify the pipe type.
- AC age: a system near the end of its life is a fair item to negotiate.
Get an insurance quote with the inspection report in hand before your inspection period ends.
- 1 bedroom$224K
- 2 bedrooms$341K
- 3 bedrooms$620K
- 4 bedrooms$853K
- 5+ bedrooms$1.29M
Zillow index by bedroom count, all home types.
- Weston$802K
- Coral Springs$640K
- Davie$625K
- Plantation$614K
- Pembroke Pines$590K
- Fort Lauderdale$587K
- Miramar$554K
- Hollywood$511K
- Sunrise$472K
- Pompano Beach$446K
- Deerfield Beach$429K
- Lauderhill$408K
- Tamarac$377K
Zillow index.
Cash you need to buy at $802,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $802,000 | $160,400 | $280,700 |
| Buyer closing costs | $1,450 | $8,504 | $7,842 |
| Total at closing | $803,450 | $168,904 | $288,542 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Lakes, drainage and flood zones
Weston sits on the western edge of Broward County against the Everglades, and much of it was built around man-made lakes that handle stormwater. Many lots back onto water. That helps drainage and views, and it also means elevation varies from street to street.
Check the FEMA flood zone for the specific address, not the neighborhood. If the house is in an A zone, your lender will require flood insurance, written through the NFIP or a private carrier. Even outside a high-risk zone, a flood policy is often inexpensive and worth pricing. Ask the seller for the elevation certificate if one exists, and ask in writing about past water intrusion or claims.
Hurricane deductibles on Florida policies are a percentage of dwelling coverage, commonly 2%, 5% or 10%, and apply once per calendar year. On $600,000 of dwelling coverage, a 2% deductible is $12,000.
HOAs, the master association and city districts
Nearly every Weston house is in an HOA, and many neighborhoods also sit under a master association that maintains entry gates, guardhouses or common landscaping. Gated neighborhoods with a staffed guard cost more each month than ungated ones. Get both the neighborhood and master fees in writing, plus any approved or planned assessments.
On top of HOA dues, the city's Indian Trace Development District levies a non-ad valorem assessment on properties in its area to maintain roads, canals and public landscaping. You will see it as a separate line on the property tax bill. Use the most recent bill to find the amount, then add it to your monthly cost estimate.
Property tax after the sale and homestead
Florida resets the assessed value to market value when a house sells. A seller who has owned since the early 2010s with homestead may have an assessed value far below the price you are paying, and their tax bill will understate yours. Estimate tax on your purchase price.
Buyers moving here full time should file for homestead with the Broward County Property Appraiser. In 2026 it takes up to $51,411 off assessed value, and Save Our Homes then caps yearly assessment increases at 3% or CPI, whichever is lower. A second home in Weston gets neither the exemption nor the 3% cap; its non-school assessment can rise up to 10% a year. Amendment 3 on the November 3, 2026 ballot would change these rules if it passes with 60%. This isn't legal or tax advice.
Cash to close on a typical Weston house
On a $802,363 house with 20% down, the down payment is about $160,473. On a $641,890 loan, note stamps at $0.35 per $100 come to about $2,247 and intangible tax at 0.2% about $1,284. Deed stamps of about $5,617 normally go to the seller. The buyer usually pays for the owner's title policy in Broward, along with the lender's policy, appraisal, survey and prepaid insurance and taxes.
Paying less a few miles away
Weston's all-homes value of about $718,627 is the highest in this part of Broward. Davie is about $515,457, Coral Springs about $521,975, Plantation about $492,003 and Pembroke Pines about $486,731. Buyers who want a similar planned-community feel at a lower price often look at Pembroke Pines and Coral Springs. Buyers who are set on Weston should decide early between an older house in a mature neighborhood and a newer one with a higher price and lower insurance. A shortlist sorted by roof age and flood zone makes that choice quicker.
Weston: questions and answers
How much does a house cost in Weston, FL?
Zillow puts the typical single-family house at about $802,363. Typical 3-bedroom homes are about $619,867 and 4-bedroom homes about $852,799.
Is Weston a good place to buy a house?
Weston is a planned suburb of mostly 1990s single-family homes with HOAs. Prices are high for Broward and were nearly flat over the past year, which suits buyers who plan to stay and want space and newer housing than most of the county.
What is the Indian Trace Development District charge?
It is a city special district assessment for roads, canals and landscaping in its area. It appears as a non-ad valorem line on the property tax bill, separate from HOA dues.
Do I need flood insurance in Weston?
Lenders require it only for homes in high-risk FEMA zones. Check the zone for the exact address, and price a policy either way, since many lots sit on lakes.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · info@danmarusinhomes.com · WhatsApp on the same number
Work out your own numbers
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.