Buying a House in Pompano Beach
A Broward city split by I-95, with old canal homes east and modest ranches west
The typical single-family house in Pompano Beach is worth about $445,858 on Zillow's home value index, down 0.8% over the past year, and a three-bedroom runs about $438,841. That is well below Fort Lauderdale for a city on the same coast, and the reason is mostly the age and mix of the houses rather than the location.
- Typical single-family home value
- $446K Pompano Beach, Zillow, September 2026
- Past year
- −0.8%
- Past 5 years
- +23.5%
- Lower third of the market
- $203K typical value
- Upper third
- $652K typical value
Pompano house prices from two bedrooms up
A two-bedroom in Pompano Beach is about $295,957, a three-bedroom about $438,841 and a four-bedroom about $577,833. Five bedrooms and up jump to about $1,067,013, nearly double the four-bedroom figure, because the largest homes are concentrated on the water east of Federal Highway.
Zillow's lower third ends near $202,669, mostly condos and smaller older homes, and the upper third begins around $652,221, where most canal and near-beach houses sit. Across all homes, values are up 21.6% over five years and down 1.3% over the past one. Condos fell 4.5% to about $245,906. For houses, the market has gone flat rather than falling, and condition separates the quick sales from the slow ones.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Single-family | All homes |
|---|---|---|
| Dec 2012 | $133,975 | $125,944 |
| Dec 2013 | $164,319 | $147,599 |
| Dec 2014 | $186,230 | $164,873 |
| Dec 2015 | $206,708 | $178,290 |
| Dec 2016 | $231,484 | $192,592 |
| Dec 2017 | $263,947 | $213,190 |
| Dec 2018 | $284,431 | $229,934 |
| Dec 2019 | $296,978 | $240,441 |
| Dec 2020 | $318,400 | $256,346 |
| Dec 2021 | $377,655 | $300,681 |
| Dec 2022 | $443,828 | $362,402 |
| Dec 2023 | $463,935 | $381,776 |
| Dec 2024 | $464,431 | $373,577 |
| Dec 2025 | $444,925 | $351,249 |
| Sep 2026 | $445,858 | $350,137 |
East of the highway and west of I-95
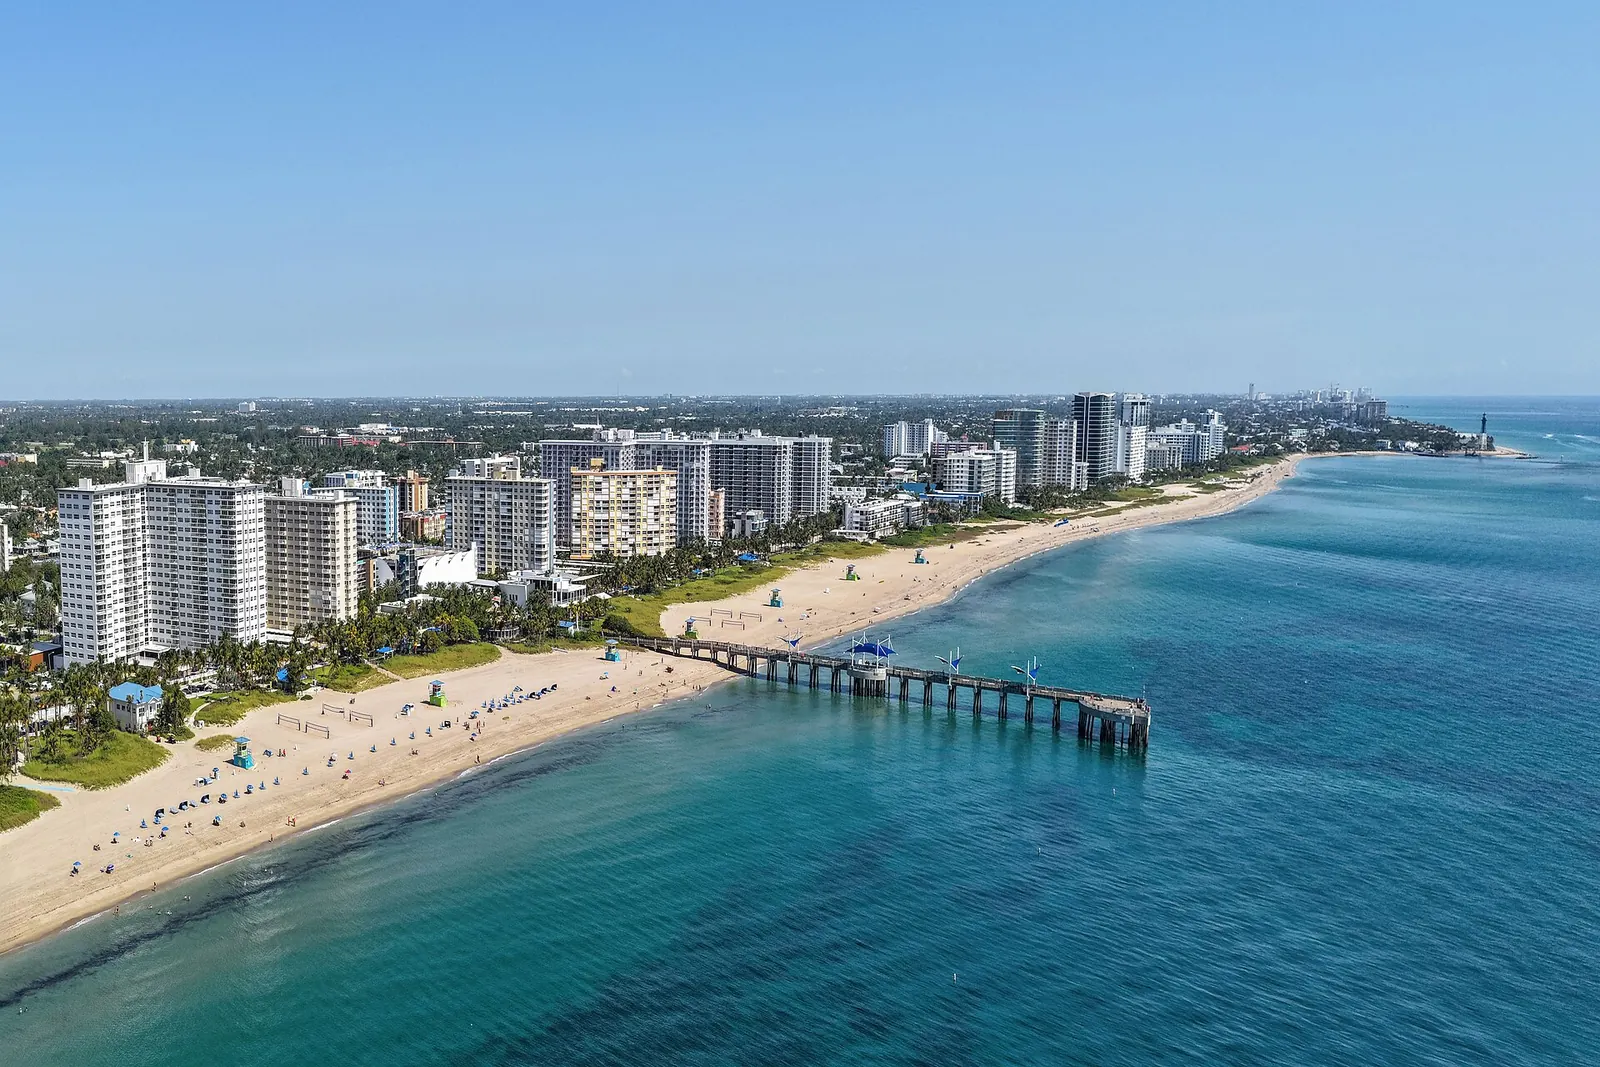
Pompano Beach is easiest to understand in bands running north to south. Along the ocean and the Intracoastal are condo buildings and waterfront homes. Between the Intracoastal and Federal Highway are older neighborhoods with many canal lots that have boat access to the Intracoastal and the Hillsboro Inlet. Between Federal Highway and I-95 are mid-century neighborhoods of smaller houses. West of I-95, homes are a mix of older ranches and later subdivisions.
Census counts only 29.0% of units as single-family detached and 49.6% in buildings with ten or more units. Houses are the minority, and canal houses an even smaller share, which is why their prices sit so far above the city average.
- 1 bedroom$167K
- 2 bedrooms$296K
- 3 bedrooms$439K
- 4 bedrooms$578K
- 5+ bedrooms$1.07M
Zillow index by bedroom count, all home types.
- Weston$802K
- Coral Springs$640K
- Davie$625K
- Plantation$614K
- Pembroke Pines$590K
- Fort Lauderdale$587K
- Miramar$554K
- Hollywood$511K
- Sunrise$472K
- Pompano Beach$446K
- Deerfield Beach$429K
- Lauderhill$408K
- Tamarac$377K
Zillow index.
Cash you need to buy at $446,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $446,000 | $89,200 | $156,100 |
| Buyer closing costs | $1,450 | $6,937 | $6,569 |
| Total at closing | $447,450 | $96,137 | $162,669 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Living with a 1974 median build year
Census puts the median year built at 1974. A typical Pompano house is a concrete block home built before modern wind codes, often renovated in stages by different owners. Insurers and inspectors focus on a handful of items.
- Roof age and permit; a tile or shingle roof near the end of its life can block coverage.
- Original cast iron drain lines under the slab, which crack over time; a camera scope tells you their condition.
- Electrical panels from brands insurers flag, and any aluminum branch wiring.
- Window and door protection: shutters or impact glass earn wind mitigation credits.
- Permits for additions, enclosed garages and converted porches, which are common on older Broward homes.
A 4-point inspection is usually required for insurance on houses this age. I'd rather a buyer spend a few hundred dollars on a sewer scope than learn about a collapsed drain line after closing.
Canal homes, seawalls and tidal flooding
Most canal neighborhoods sit low, and many are in FEMA high-risk zones where a lender will require flood insurance. Some streets near the Intracoastal see water during the highest seasonal tides even without a storm. Ask the seller how the street handles king tides, look for water lines on seawalls and driveways, and get the elevation certificate.
The seawall is part of the house purchase. Broward County has adopted minimum seawall elevation standards that apply when walls are built or substantially repaired, so an old, low seawall may need to be raised when it is replaced. Hire a marine contractor to inspect it, and ask about dock permits and any shared wall issues with neighbors.
Flood insurance on a canal house can be a large line in the budget. Ask the seller for their current flood declarations page, since an existing NFIP policy can sometimes be assumed by the buyer and may carry a better rate than a new one. Then get your own quote, private and NFIP, before the inspection period ends, and compare them with the wind policy as one combined annual cost.
Broward closing costs and the tax reset
In Broward the seller usually pays deed stamps at $0.70 per $100, and by local custom the buyer often pays for the owner's title policy, so budget for it. With 20% down on a $445,858 house, the loan is about $356,686, which means about $1,248 in note stamps and $713 in intangible tax. Add the lender's title policy, survey, inspections and the first year of wind and flood premiums.
Broward's property appraiser will reassess the house at market value for the year after you buy. A permanent Florida resident can claim homestead, worth up to $51,411 off assessed value in 2026, with Save Our Homes then holding increases to 3% or CPI. Census shows 13.3% of Pompano homes are seasonal, and those owners pay without homestead, with only the 10% non-school cap.
How Pompano compares with nearby Broward cities
On Zillow's all-homes figures, Pompano Beach at $350,137 sits well below Fort Lauderdale at $509,743, Coral Springs at $521,975 and Weston at $718,627. Deerfield Beach, just north, is about $271,903, and Tamarac about $291,266, both pulled down by large condo and 55+ stocks. Census shows a median age of 41.3 and 19.3% of residents 65 or older.
Pompano tends to suit buyers who want a canal home with ocean access for less than Fort Lauderdale prices, or a block house near the beach they can update over time. Buyers who want newer construction usually look west, toward Coral Springs. A shortlist sorted by east or west of I-95 and by roof age gets you to the right houses quickly.
Quick answers
How much does a house cost in Pompano Beach?
Zillow's index puts the typical single-family home at about $445,858. A three-bedroom runs about $438,841 and a four-bedroom about $577,833.
Is Pompano Beach cheaper than Fort Lauderdale?
Yes. All home types in Pompano Beach average about $350,137 versus about $509,743 in Fort Lauderdale on Zillow's index.
Who pays title insurance in Pompano Beach?
In Broward the buyer customarily pays for the owner's title policy, though the contract can assign it to the seller. The premium itself is a state-set rate.
Do Pompano Beach canal homes flood?
Many canal lots are in FEMA high-risk zones and some streets see tidal flooding. Check the elevation certificate, flood history and seawall height for each house.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · info@danmarusinhomes.com · WhatsApp on the same number
Calculators for this purchase
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.