Buying a Condo in Miami
Where condo prices stand after the reserve laws, and how to pick a building that will hold up
A typical Miami condo is worth about $383,531 on Zillow's home value index, down 1.6% over the last year, while single-family homes in the city rose 2.3% to $664,415. That gap is the whole story of the Miami condo market right now: buyers are paying for the building as much as the unit, and older buildings with thin reserves are being priced down. Here is how I would approach a purchase in 2026.
- Typical condo value
- $384K Miami, Zillow, September 2026
- Past year
- −1.6%
- Past 5 years
- +29.6%
- Lower third of the market
- $353K typical value
- Upper third
- $982K typical value
Why Miami condo values slipped while houses kept rising
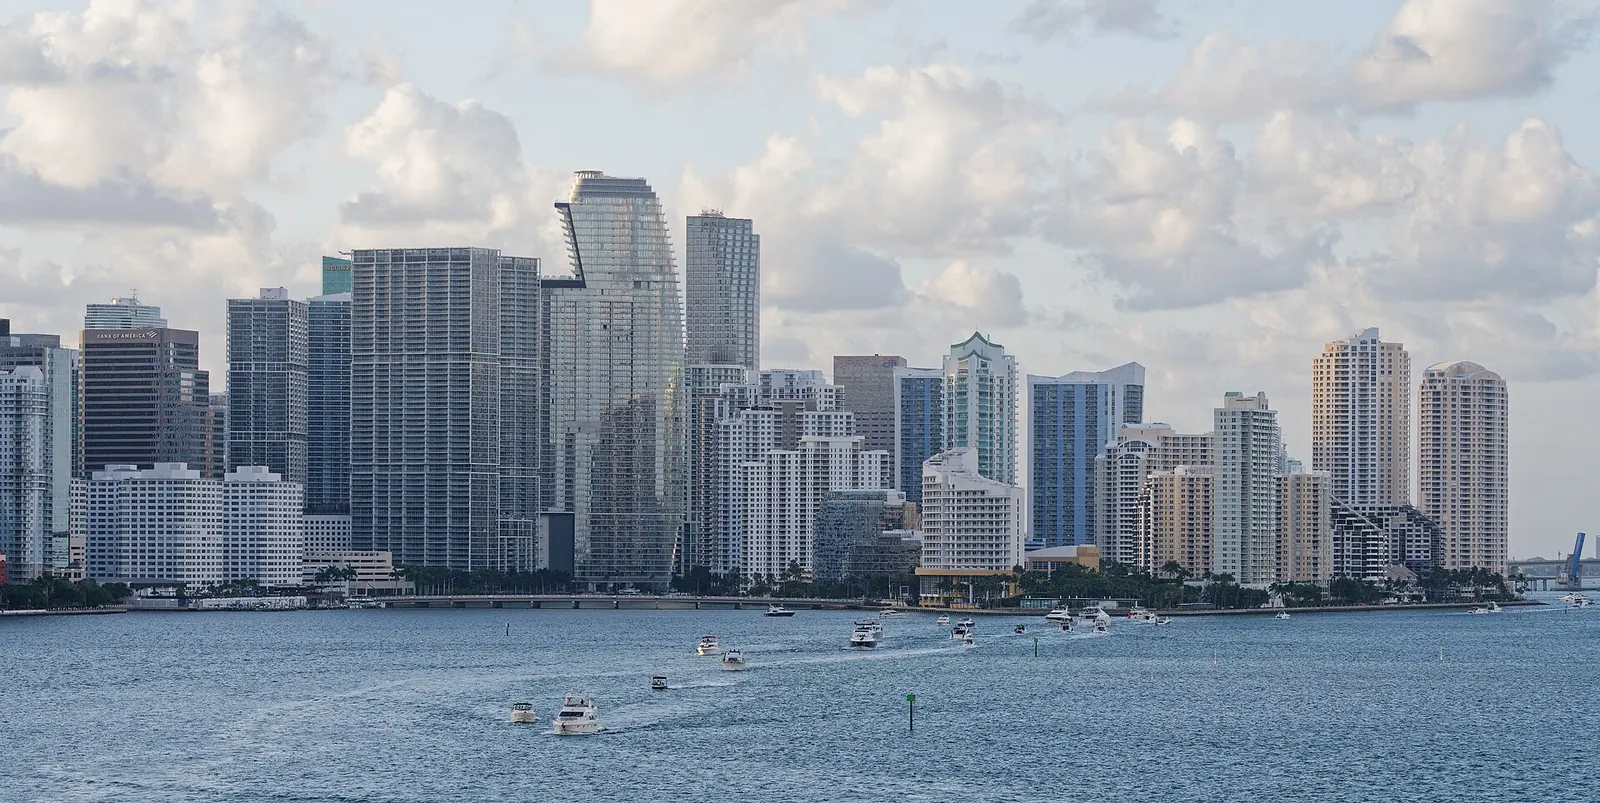
Miami is a condo city. Census data shows 55.3% of all housing units sit in buildings with 10 or more units, and only 22.4% are detached single-family homes. The median year built for the city's housing is 1979, so a large share of the tower and mid-rise stock is more than 40 years old.
After the 2021 Surfside collapse, Florida rewrote the rules for condo associations. Buildings of three or more habitable stories now need milestone structural inspections and a Structural Integrity Reserve Study (SIRS) every 10 years, and for budgets adopted on or after December 31, 2024, owners can no longer vote to waive or cut those reserves. In older Miami buildings that has meant higher monthly fees, special assessments, or both.
Those costs land on owners, and buyers price them in. That is the most practical explanation for a condo index that is slightly down while houses are up. It also means the spread between a well-funded building and an underfunded one can be wide, even on the same street.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Condos | All homes |
|---|---|---|
| Dec 2012 | $198,880 | $200,649 |
| Dec 2013 | $249,891 | $248,094 |
| Dec 2014 | $274,196 | $275,156 |
| Dec 2015 | $285,546 | $305,102 |
| Dec 2016 | $279,385 | $320,420 |
| Dec 2017 | $270,054 | $331,646 |
| Dec 2018 | $269,437 | $343,305 |
| Dec 2019 | $265,611 | $353,119 |
| Dec 2020 | $271,214 | $374,584 |
| Dec 2021 | $313,008 | $431,724 |
| Dec 2022 | $396,464 | $527,235 |
| Dec 2023 | $414,355 | $566,529 |
| Dec 2024 | $407,756 | $593,035 |
| Dec 2025 | $386,807 | $577,203 |
| Sep 2026 | $383,531 | $583,705 |
What a Miami condo budget buys by bedroom count
Zillow's bedroom figures cover all home types, but in a city this dense they track the condo market closely at the smaller sizes:
- 1 bedroom: about $351,134
- 2 bedrooms: about $450,924
- 3 bedrooms: about $620,623
Going from one bedroom to two adds roughly $100,000. That jump matters more than it looks, because monthly association fees in most buildings are allocated by unit size, so the second bedroom raises both the price and the carrying cost.
Nearby cities give useful reference points. Aventura's typical home value is about $423,482 and North Miami Beach about $452,705, both heavily condo markets north of the city. Coral Gables, at $1,571,133, is a different price world altogether.
- 1 bedroom$351K
- 2 bedrooms$451K
- 3 bedrooms$621K
- 4 bedrooms$785K
- 5+ bedrooms$1.27M
Zillow index by bedroom count, all home types.
- Coral Gables$567K
- Miami Beach$460K
- Aventura$408K
- Doral$389K
- Miami$384K
- Fountainbleau$281K
- The Hammocks$275K
- Cutler Bay$262K
- Hialeah$245K
- North Miami Beach$232K
- Homestead$223K
- North Miami$181K
- Miami Gardens$174K
Zillow index.
Cash you need to buy at $384,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $384,000 | $76,800 | $134,400 |
| Buyer closing costs | $3,445 | $8,660 | $8,343 |
| Total at closing | $387,445 | $85,460 | $142,743 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees, plus the owner's title policy, which Miami-Dade buyers usually pay. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Reading the association documents before your 7-day window closes
Since July 1, 2025, a resale condo buyer in Florida can cancel within 7 days (excluding weekends and legal holidays) after receiving the association documents. In Miami, that week is where most of the real decision gets made. I ask for and read, in this order:
- The milestone inspection report and whether any phase two repairs were recommended. A building that turned 30 is due by December 31 of that year, then every 10 years.
- The SIRS and the current reserve balance against what the study says should be there.
- Board minutes from the last 12 to 24 months. Special assessments are usually discussed long before they are voted.
- The current budget, including the master insurance premium and how much it changed at the last renewal.
- Pending litigation involving the association.
A low monthly fee in a 1970s building is a warning sign more often than a bargain. If the reserves are far below the study, someone will pay to close that gap, and it is usually the owners who own the units when the bill arrives.
Financing: warrantable vs non-warrantable Miami buildings
Conventional lenders want a building to meet agency guidelines before they will lend at standard terms. Buildings with major unfinished structural repairs, significant litigation, a high share of units owned by one entity, or large commercial space can fall outside those rules and become non-warrantable.
A non-warrantable building does not stop a sale, but it changes it. Expect a larger down payment, a different loan product with a higher rate, and fewer buyers when you sell later. Cash buyers are common in Miami for exactly this reason. If you are financing, have your lender review the condo questionnaire early, before inspection money is spent.
On closing costs, a buyer with a mortgage pays Florida's note stamps of $0.35 per $100 and intangible tax of 0.2% of the loan. On an 80% loan against a $383,531 condo, about $306,825, that is roughly $1,074 in note stamps and $614 in intangible tax. In Miami-Dade, the buyer customarily pays for the owner's title policy, which is a state-set rate.
Building insurance, flood exposure and what you insure yourself
The association's master policy covers the structure, and its premium is part of your monthly fee. As an owner you carry an HO-6 policy for interior finishes, contents and liability, plus loss assessment coverage, which helps if the association passes an uninsured loss or hurricane deductible on to owners.
Ask what the building's hurricane deductible is. Florida hurricane deductibles are a percentage of the insured value, and for a high-rise that can be a large dollar figure split among owners. Ask whether the building carries flood coverage, and check the FEMA flood zone of the address yourself. Units on higher floors still share the cost of a flooded lobby, garage or electrical room.
Lifestyle rules that affect resale value
Read the declaration and rules for pet limits, weight limits for dogs, renovation hours, and minimum lease terms. Even if you plan to live in the unit, a building with tighter rules can have a smaller pool of future buyers, which affects how quickly you can sell. Some buyers want those limits; others walk away because of them. Knowing which group your building appeals to helps you set a realistic resale expectation.
If you tell me your budget, bedroom count and how much monthly fee you can carry, I can narrow Miami's buildings to a shortlist with the reserve and inspection status already checked.
What buyers ask me
Should I buy a condo in Miami in 2026?
It depends on the building more than the city. Zillow shows Miami condo values down 1.6% over the past year, which gives buyers some room, but the right purchase is a unit in a building with a current milestone inspection, a funded SIRS and no surprise assessments in the minutes.
How much are condo fees in Miami?
They vary widely by building age, amenities, insurance and reserve funding. Older buildings catching up on required reserves often have the highest increases. Compare fees per square foot and read the budget rather than looking at the monthly number alone.
Can I back out of a Miami condo purchase after reading the documents?
Yes. Resale condo buyers in Florida can cancel within 7 days, excluding weekends and legal holidays, after receiving the association documents. New construction buyers have 15 days.
Can a foreigner buy a condo in Miami?
Yes, no citizenship or residency is needed, and buying does not create a visa. Foreign national loans usually need 30 to 40% down. Florida's SB 264 restricts buyers domiciled in certain countries near military sites and critical infrastructure, so check that before you sign.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · info@danmarusinhomes.com · WhatsApp on the same number
Work out your own numbers
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.