Buying a Condo in Hialeah
Some of the lowest condo prices in central Miami-Dade, in buildings that need a careful read.
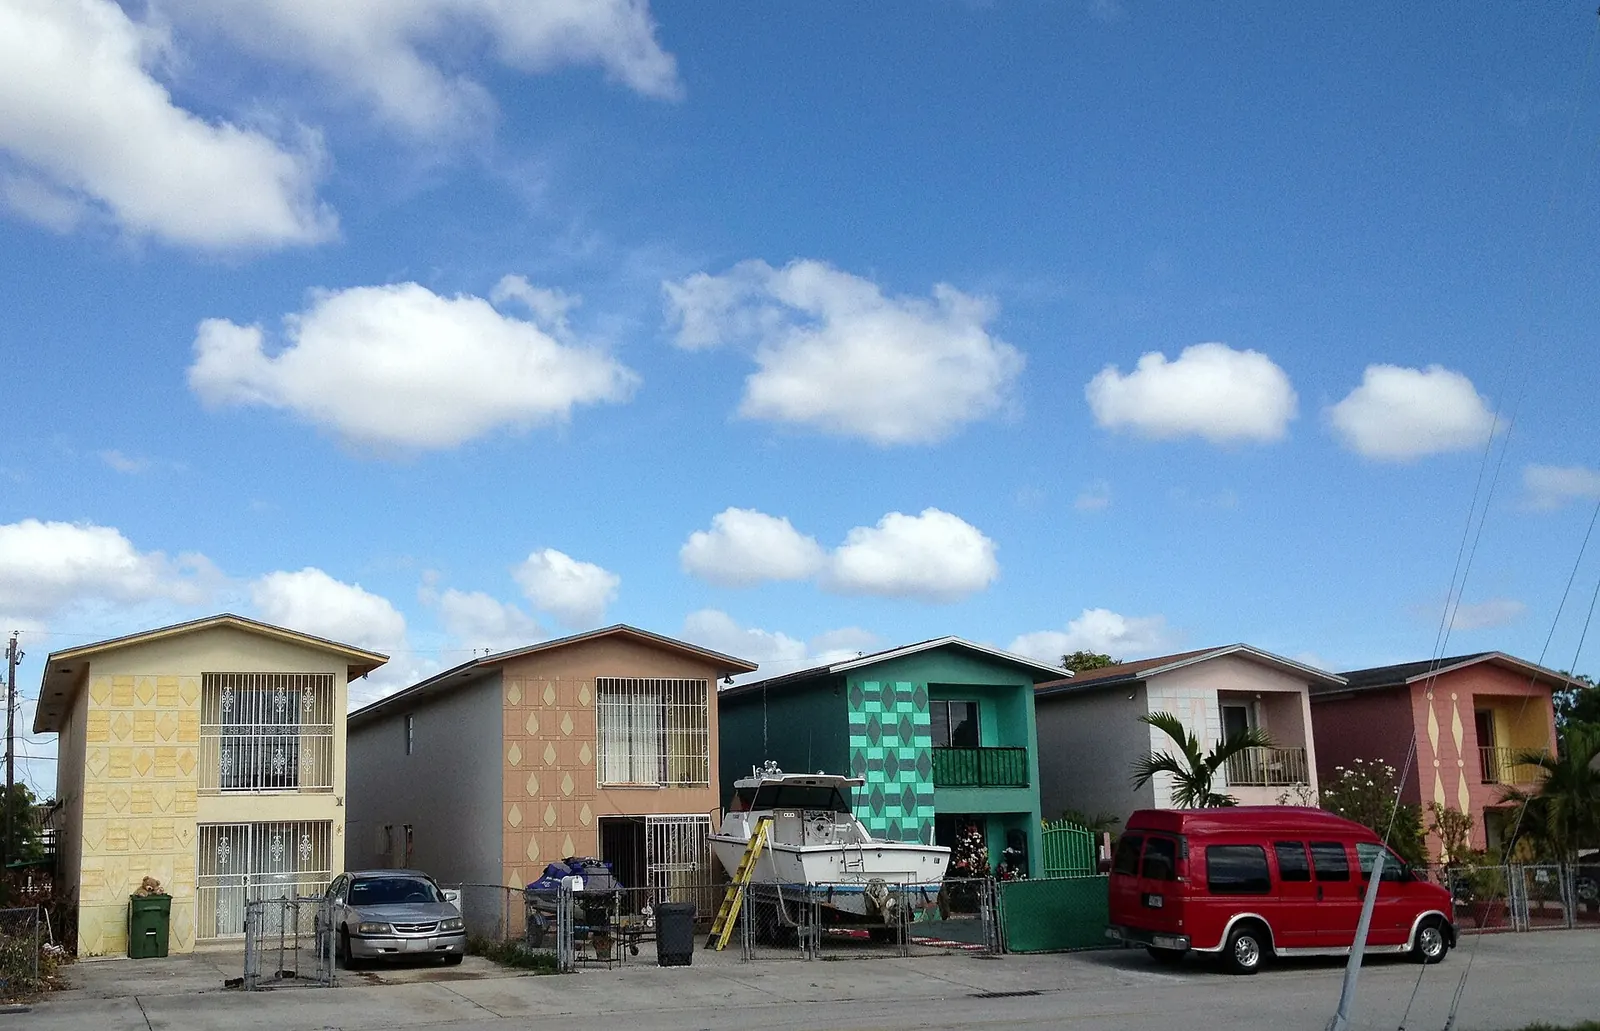
A typical Hialeah condo is worth about $245,397 on Zillow's home value index, down 4.4% over the past year, which is less than half the city's typical house at $565,104. The low price is real, and so is the reason behind much of it: Hialeah's housing is old, with a median year built of 1975, and older condo buildings are carrying the heaviest costs under Florida's post-2022 condo laws.
- Typical condo value
- $245K Hialeah, Zillow, September 2026
- Past year
- −4.4%
- Past 5 years
- +23.6%
- Lower third of the market
- $248K typical value
- Upper third
- $628K typical value
What $185,000 to $270,000 buys
Zillow's figures put a typical Hialeah one-bedroom at about $184,724 and a two-bedroom at about $265,592. The lower third of the whole market runs up to about $248,120, and condos make up most of it. Three-bedroom homes jump to $531,319, a price where you are almost always buying a house, so a condo search here is mostly a one- and two-bedroom search.
Compared with nearby markets, those numbers are low. Doral's typical condo is about $388,810. Aventura's all-homes figure, a market made up largely of condo towers, is $423,482. A buyer who wants a Miami-Dade address, rail access and a short drive to the airport for under $270,000 will find more choices in Hialeah than in most neighboring cities.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Condos | All homes |
|---|---|---|
| Dec 2012 | $74,689 | $121,176 |
| Dec 2013 | $91,710 | $144,305 |
| Dec 2014 | $109,835 | $166,603 |
| Dec 2015 | $124,376 | $189,960 |
| Dec 2016 | $142,130 | $216,951 |
| Dec 2017 | $155,509 | $241,665 |
| Dec 2018 | $165,668 | $261,217 |
| Dec 2019 | $171,802 | $274,713 |
| Dec 2020 | $182,432 | $297,281 |
| Dec 2021 | $205,192 | $334,049 |
| Dec 2022 | $246,317 | $397,528 |
| Dec 2023 | $273,541 | $436,628 |
| Dec 2024 | $275,257 | $458,382 |
| Dec 2025 | $252,447 | $442,860 |
| Sep 2026 | $245,397 | $443,765 |
Why a 1970s building changes the math
Census data shows 36.3% of Hialeah's housing units sit in buildings of ten or more units, and many of these were built in the 1960s through the 1980s. A building with three or more habitable stories must complete a milestone inspection by Dec 31 of the year it turns 30, then every 10 years. For most Hialeah condo buildings, that deadline has already passed, so the first question is whether the inspection is done and what it found.
Those buildings also need a Structural Integrity Reserve Study every 10 years, covering the roof, structure, fireproofing, plumbing, electrical, windows and waterproofing. For budgets adopted on or after Dec 31, 2024, owners can't vote to skip or reduce those reserves. In an older building that saved little for decades, that means higher monthly fees, a special assessment, a loan the association takes out and repays through dues, or some combination of all three.
A two-story garden complex falls outside the milestone rule, but it still has roofs, plumbing and paving to fund. Ask for its reserve schedule all the same. Smaller associations with a few dozen units also have fewer owners to share a big repair bill, so the same roof costs each owner more.
- 1 bedroom$185K
- 2 bedrooms$266K
- 3 bedrooms$531K
- 4 bedrooms$655K
- 5+ bedrooms$743K
Zillow index by bedroom count, all home types.
- Coral Gables$567K
- Miami Beach$460K
- Aventura$408K
- Doral$389K
- Miami$384K
- Fountainbleau$281K
- The Hammocks$275K
- Cutler Bay$262K
- Hialeah$245K
- North Miami Beach$232K
- Homestead$223K
- North Miami$181K
- Miami Gardens$174K
Zillow index.
Cash you need to buy at $245,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $245,000 | $49,000 | $85,750 |
| Buyer closing costs | $2,750 | $7,353 | $7,151 |
| Total at closing | $247,750 | $56,353 | $92,901 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees, plus the owner's title policy, which Miami-Dade buyers usually pay. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Documents to read in the 7-day window
Florida law gives resale condo buyers 7 days, excluding weekends and legal holidays, to cancel after receiving the association documents. In a Hialeah building, I'd use those days on:
- The milestone inspection report and any Phase 2 repair list.
- The SIRS and the current budget's reserve line for each component.
- Board minutes from the past 12 to 24 months, which often show assessments before they're voted.
- The master insurance policy, its premium and the hurricane deductible.
- The share of owners behind on dues, and any lawsuits.
An approved but unpaid special assessment can usually be negotiated with the seller. One that is still being discussed is harder to price, so get the board's estimate in writing if you can.
Getting a loan on a Hialeah condo
Many older buildings have trouble meeting conventional loan standards. Lenders look at reserve funding, delinquency rates, pending litigation and unfinished structural repairs, and a building that fails becomes non-warrantable. That narrows the buyer pool to cash buyers and portfolio loans with larger down payments.
It cuts both ways. A non-warrantable unit can be cheaper for a cash buyer, and harder to resell later. Ask your lender to run the condo questionnaire before your inspection money is spent. On a $245,397 unit with 20% down, the note stamps and intangible tax come to roughly $1,080. Miami-Dade's deed stamps for a condo, at $0.60 plus the $0.45 surtax per $100, are about $2,577 and usually the seller's cost. The buyer typically pays for the owner's title policy in this county. This isn't legal or tax advice.
Insurance, flood and the monthly total
Your monthly cost has four parts: the mortgage, the condo fee, your HO-6 policy and property taxes. The fee is the part most likely to change. Ask for the last three years of budgets to see how fast it has risen, and plan for it to keep rising in an older building.
Hialeah is low-lying and laced with canals. Check the building's FEMA flood zone and ask whether the association carries flood insurance on the structure. Add loss assessment coverage to your HO-6 so a share of the master policy's hurricane deductible doesn't land on you uninsured after a storm.
Homestead and the tax bill
If the condo will be your permanent home, file for the homestead exemption: up to $51,411 off assessed value in 2026, with future increases in assessed value limited to 3% or inflation. Florida has no state income tax. The assessment resets to market value after the sale, so many long-time owners in Hialeah pay far less than a new buyer will. Use your purchase price to estimate the bill.
When the price is low because the building has already done its repairs and funded its reserves, that is a good buy. When it is low because the work hasn't started, the real price includes the assessment to come. Sorting those two is most of the job, and a shortlist of buildings with clean paperwork is where I'd start.
Questions buyers ask
How much is a condo in Hialeah?
Zillow's typical Hialeah condo value is about $245,397. One-bedrooms run near $184,724 and two-bedrooms near $265,592.
Is Hialeah a good place to buy a condo?
It offers some of the lowest condo prices in central Miami-Dade. The risk is in older buildings, so read the milestone inspection, reserve study and minutes before you commit.
Why are Hialeah condos so cheap?
Much of the stock is from the 1960s to 1980s, and Florida's newer condo laws require older buildings to fund repairs and reserves. Condo values also fell 4.4% over the past year.
Can I get a mortgage on an older Hialeah condo?
Often, but some buildings are non-warrantable because of low reserves, high delinquencies or open repairs. Have your lender review the building before you pay for inspections.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · info@danmarusinhomes.com · WhatsApp on the same number
Check the costs yourself
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.